
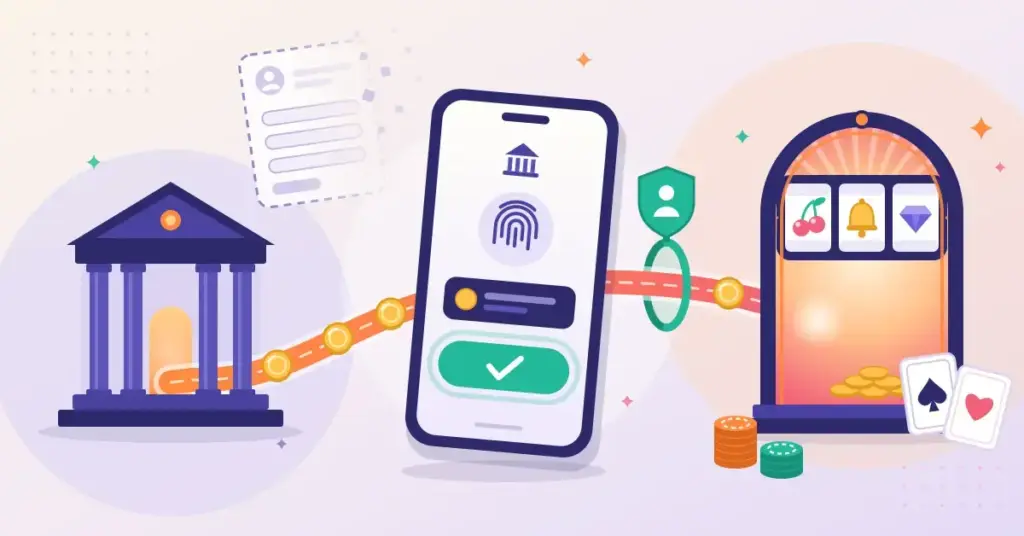
A Pay N Play casino is an online casino you can deposit into and start playing at without filling in a traditional registration form. Instead of creating a username and password and uploading identity documents, you log in through your own online banking, confirm a deposit, and begin playing within seconds. The model was built by the Swedish payments company Trustly and launched in 2016, and it is the reason the phrase “verification-free” gets attached to this kind of casino. That phrase is misleading, though: the sign-up form disappears, but identity checks do not. This guide explains exactly how the flow works, where it is genuinely available, and what it means for players in New Zealand, where a new licensing regime took effect in 2026. It is background information, not a recommendation to sign up or gamble.
Key Points
- What it is: a casino you deposit into and start playing at with no registration form — the bank login creates your account.
- Who built it: the Swedish payments company Trustly, which launched Pay N Play in 2016.
- “Verification-free” is about the form, not the checks: your bank still verifies your identity and passes that data to the casino.
- Two versions: pure (bank login is the only way in) and hybrid (bank login sits beside a normal registration form).
- Where it works: mainly Sweden, Finland, Estonia, the Netherlands and the UK, helped by national electronic IDs like BankID.
- New Zealand: the native product is not offered here; local open-banking bank transfers provide the rails, but a verified account is still required.
- 2026 law: licensed NZ operators are reporting entities under the AML/CFT Act 2009 and must carry out customer due diligence, so a truly verification-free account cannot be offered lawfully.
What is a Pay N Play casino?
A Pay N Play casino replaces the usual “register, then deposit” sequence with a single bank-authenticated payment that doubles as your account. “Pay N Play” is a product name coined by Trustly, a payments firm founded in Sweden in 2008 that specialises in account-to-account bank transfers, which launched the product in 2016. The model spread quickly across the Nordic market before appearing elsewhere in Europe.
The core idea is that the bank login you already trust handles three jobs at once: it proves who you are, it moves your money, and it creates your playing session. Because you never type in personal details or choose a password, the experience feels like paying for anything else through your banking app. The casino, meanwhile, receives verified account and identity data from your bank behind the scenes. This is why the model is sometimes called a “no account” or “no registration” casino, even though a player record still exists on the operator’s side.
How verification-free deposits actually work
The deposit is the account: a Pay N Play session starts the moment your bank confirms the first payment. There is no separate sign-up step before it. In a pure Pay N Play flow, the steps look like this:
- You open a participating casino and select “Deposit and Play” (or similar) rather than a “Register” button.
- You choose your bank from a list of supported institutions.
- You log in to that bank using its own security — in the Nordic countries this is usually BankID, a government-grade electronic ID.
- You approve a deposit amount. The transfer runs directly from your bank account to the casino.
- Your balance appears and you can play immediately. The operator has already created your account using the data the bank passed across.
When you want to cash out, winnings are sent back to the same bank account the deposit came from, so there is no separate payout form to fill in either. That closed loop — money out and money in through one verified account — is central to the model’s appeal.
Where the “verification-free” label comes from — and why it overstates things
“Verification-free” refers to the player experience, not the compliance that happens underneath it. What you skip is the manual work: no registration form, no chosen password, and usually no uploading of ID documents at the point of signing up. What still happens is identity verification — it is simply done by your bank and handed to the casino as part of the payment. According to Trustly’s Pay N Play product page, the service uses Open Banking and know-your-customer (KYC) data to verify a player’s identity as they make the deposit, then passes that verification to the casino in a single flow. KYC is the “know your customer” process a regulated gambling operator runs to confirm who a player is.
In other words, a Pay N Play casino is not anonymous and it does not remove identity checks. It moves those checks to the bank login, where they are faster and invisible to you. If an operator later needs extra documents — for example, when a large withdrawal triggers a manual review — it can still ask for them.
Pay N Play vs a Standard Casino Account
| Feature | Pure Pay N Play | Standard casino account |
|---|---|---|
| Registration form | None — the deposit creates the account | Required before you can play |
| Login method | Your online banking (e.g. BankID) | Username and password you create |
| Identity / KYC | Supplied by your bank during the deposit | Collected at sign-up, often with document uploads |
| Deposit method | Direct bank transfer only | Cards, e-wallets, bank transfer and more |
| Withdrawals | Returned to the same bank account automatically | Chosen from your saved payout methods |
| Where it is offered | Mainly Sweden, Finland, Estonia, Netherlands, UK | Most licensed markets worldwide |
| New Zealand availability | Not offered in native form | Standard model used by licensed operators |
Pure and hybrid Pay N Play: two different models
Not every casino that advertises Pay N Play works the same way. In practice the model appears in two forms, and the difference matters for how “registration-free” the experience really is.
- Pure Pay N Play: Trustly’s bank login is the only way to register, log in and pay. There is no username or password at all — you return to the casino by authenticating through your bank again. This is the cleanest version of the model.
- Hybrid Pay N Play: the bank-login flow sits alongside a conventional registration form as one option among several. Players who prefer a traditional account can still create one, while others use the faster bank route.
Because the hybrid version keeps a normal account path, calling it a “no account” casino is an oversimplification. When you read that a casino offers Pay N Play, it is worth checking which of the two models it actually runs.
Which banks and countries support Pay N Play?
Pay N Play only works where Trustly connects to local banks, and that coverage is concentrated in a handful of European markets. Trustly’s Pay N Play product page lists the service as available in Sweden, Finland, Estonia, the Netherlands and the United Kingdom. Availability changes over time and varies by operator, so any country list should be treated as a snapshot rather than a fixed rule.
The model works best in countries with a widely used national electronic ID. In the Nordic region, BankID lets a player prove their identity instantly inside their banking app, which is what makes the “log in and play” experience so smooth. Where no equivalent national ID exists, the flow is harder to replicate because the bank cannot hand over the same verified identity in one step.
Is Pay N Play available in New Zealand?
New Zealand is not among the markets Trustly lists for Pay N Play, so the native product is not offered to players here. The country also has no single national electronic ID like BankID that a casino could plug into. The genuine Nordic-style “log in through your bank and play with no form” experience therefore does not exist here in the same way, regardless of what some offshore sites advertise.
What New Zealand does have is a fast-maturing open-banking framework that provides the same underlying rails — direct, account-to-account bank payments. Under the Customer and Product Data Act 2025, regulated payment initiation went live for the main banks (ANZ, ASB, BNZ and Westpac) from December 2025, with Kiwibank following in 2026. That is the plumbing a Pay N Play-style flow needs, and it already powers the broader category of instant bank transfer casinos. The difference is that New Zealand’s version still expects you to hold a verified casino account; it does not fold registration and identity into a single tap the way the Nordic product does. If your main interest is getting money in and out quickly, the more relevant local comparison is between the fastest payout online casinos in NZ and the practical side of how to withdraw money from an online casino.
Pay N Play and New Zealand’s 2026 online casino law
New Zealand’s new licensing regime makes a truly “verification-free” account impossible to offer lawfully, because customer due diligence is mandatory. The Online Casino Gambling Act 2026 came into force on 1 May 2026 and created the country’s first licensing system for online casinos, administered by the Department of Internal Affairs (DIA). The law has extraterritorial reach, and advertising to New Zealanders by unlicensed operators has been prohibited since 1 May 2026.
The DIA is issuing a limited number of licences — up to 15 — through a competitive process that runs in stages: an expression-of-interest round, an auction, and then a formal licence application. From 1 December 2026, providers are required to cease conducting online casino gambling in New Zealand unless they have applied for an online casino gambling licence. Licensed operators are reporting entities under the Anti-Money Laundering and Countering Financing of Terrorism Act 2009, so they must carry out customer due diligence rather than let a player deposit and withdraw real money anonymously.
The practical takeaway is simple. Even if a bank-login deposit flow appears at a New Zealand-facing casino, it will sit on top of the operator’s customer due diligence obligations, not replace them. The convenience Pay N Play markets — no form to fill in — can be partly delivered by open banking, but the identity check behind it is a legal requirement, not an optional extra.
Pros and cons of the Pay N Play model
The model trades a small amount of control for a lot of speed, and whether that suits you depends on how you value each side.
Potential advantages:
- Fast onboarding: there is no form, no email confirmation and no password to remember.
- Bank-grade security: you authenticate with your own bank’s login rather than handing new credentials to the casino.
- A closed money loop: withdrawals return to the same verified bank account, which reduces payment errors.
- Less data entered manually: you do not type personal details into a sign-up form, because the bank supplies them.
Trade-offs and limits:
- Limited availability: it only works where Trustly supports local banks and, ideally, a national electronic ID.
- Not anonymous: your identity is still verified; the checks are just hidden from view.
- Withdrawal speed still depends on the operator: a fast deposit does not guarantee an instant payout if a manual review is triggered.
- Speed can encourage impulsive play: removing friction from depositing is convenient, but it can also make it easier to spend more than intended.
Two clarifications are worth keeping in mind. Pay N Play is an onboarding and payment method, not an offer, so it is unrelated to low deposit casinos or sign-up promotions. And if your goal is quick, familiar payments rather than registration-free sign-up, e-wallet routes such as PayPal casino alternatives cover similar ground.
Responsible Gambling Disclaimer
This article is background information about a payment and onboarding model. It is not a recommendation to gamble, and it does not describe a way to avoid identity checks or improve your chances of winning. Online casino gambling involves real financial risk, and no payment method changes the odds of any game. It is intended for adults only.
If gambling is causing you or someone you know harm, free and confidential help is available. You can contact the Gambling Helpline Aotearoa on 0800 654 655 or by texting 8006, and find support and self-help tools through local responsible gambling resources. Set deposit and time limits before you play, and never gamble money you cannot afford to lose.
Sources
- Trustly — Pay N Play product page (markets, KYC and Open Banking flow)
- Wikipedia — Trustly (founded 2008; Pay N Play launched 2016)
- Department of Internal Affairs — Online casino gambling regulation
- Department of Internal Affairs — Online Casino Gambling (Minimum Standards) 2026
- Russell McVeagh — Online Casino Gambling Bill passes its final reading
- Simpson Grierson — House rules: New Zealand’s new online casino regime
- Gambling.com — New Zealand online casino licence auction set for September
- NZ Adviser / MPA — Open banking goes live in New Zealand
- Gambling Helpline Aotearoa
Frequently Asked Questions (FAQ)
Does Pay N Play really skip identity verification?
No. It skips the manual registration form and the document upload at sign-up, but your identity is still verified — your bank confirms who you are during the deposit and passes that data to the casino. The model moves verification to the bank login rather than removing it.
Who created Pay N Play?
Pay N Play is a product from Trustly, a Swedish payments company that specialises in direct bank transfers. It launched in 2016, and the model became popular first in the Nordic market.
Can New Zealand players use a Pay N Play casino?
Not in its original form. Trustly’s Pay N Play relies on local bank connections and a national electronic ID such as BankID, neither of which is set up for New Zealand. New Zealand instead uses open-banking bank transfers, which provide fast account-to-account payments but still expect a verified casino account.
Is Pay N Play legal under New Zealand’s 2026 rules?
The payment concept is not banned, but a casino offering it to New Zealanders must hold a licence under the Online Casino Gambling Act 2026 and must still identify its customers. A genuinely verification-free account cannot be offered lawfully, because licensed operators are reporting entities under New Zealand’s Anti-Money Laundering and Countering Financing of Terrorism Act 2009 and must carry out customer due diligence.
How are withdrawals handled at a Pay N Play casino?
Winnings are sent back to the same bank account used for the deposit, so there is no separate payout form. The transfer is often fast, but operators can still delay a withdrawal for routine checks, particularly on larger amounts, so “instant” is not guaranteed.